

What if your first institutional investor was also your last? What if instead of optimizing for the next round, you optimized for building a robust business: capital efficient, technically advantaged, with a clear path to a meaningful outcome?
I was at a dinner recently, put on by Makena Capital. Peter Walker from Carta presented his State of Venture report, and buried inside the data is something that should concern every LP, every founder, and frankly, every investor who thinks they’re playing a diversified game and more capital is always just over the horizon.
Valuations Are Going Parabolic at the Top, While the Middle Gets Left Behind
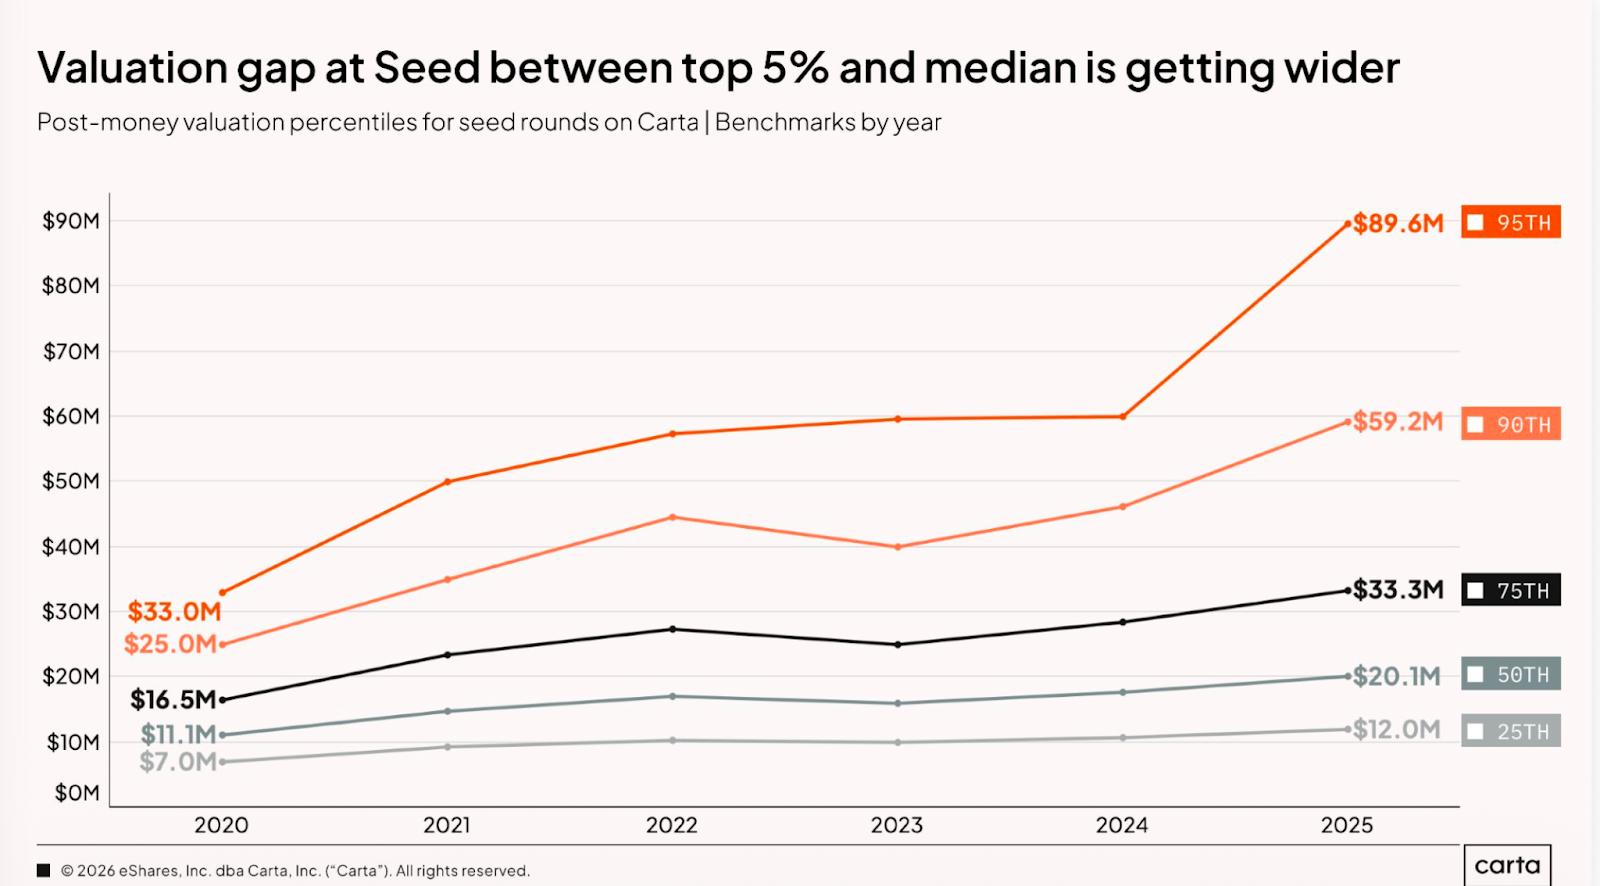
Carta’s data tells a stark story. At the seed stage, the 95th percentile valuation hit $89.6M in 2025, nearly three times where it started in 2020. Meanwhile, median seed valuations sit at a comparatively modest $20M.
At Series A, the top 5% of deals are now being done at $300M post-money and median Series A valuations have barely budged from where they were five years ago.
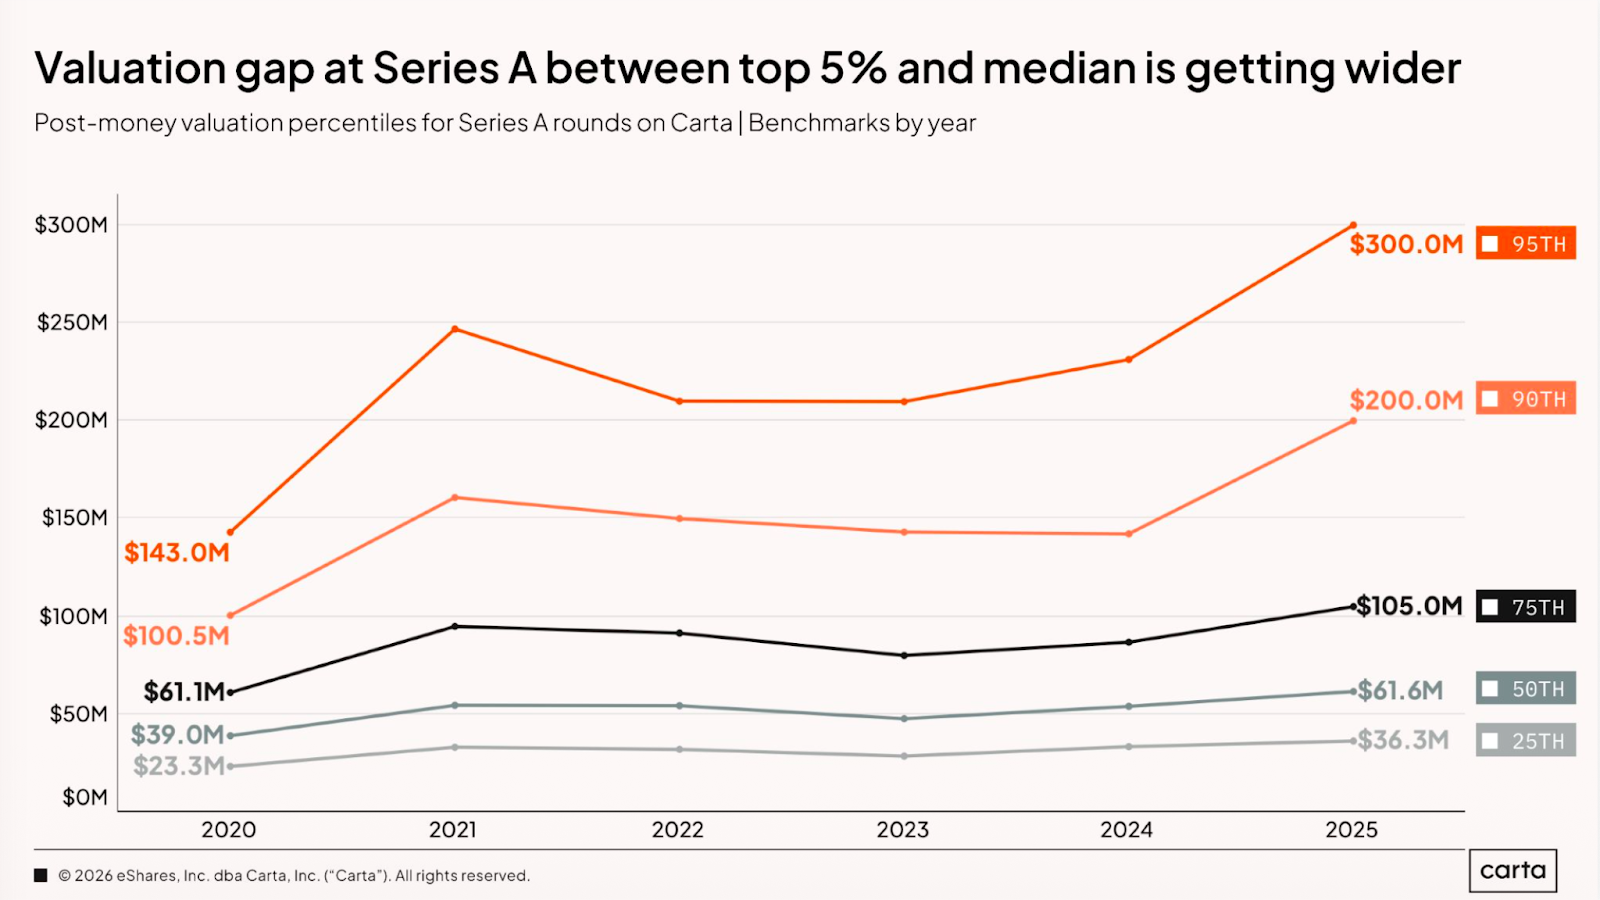
This isn’t a slow gradual takeoff. It’s vertical takeoff for a handful of AI-adjacent companies while the rest of the market never gets off the runway.
The implication is obvious once you see it: capital is concentrating at the extremes. Massive funds write massive checks into a small number of highly visible, highly competitive deals, all while an expanding fleet of exceptional, capital-efficient businesses get overlooked.
The Secondary Market Tells You Everything
Perhaps the most telling data point in the entire Carta report is the secondary market breakdown. The top 10 private companies capture 76% of all secondary demand. SpaceX, Anthropic, Anduril, xAI, OpenAI - five companies alone - account for nearly half.
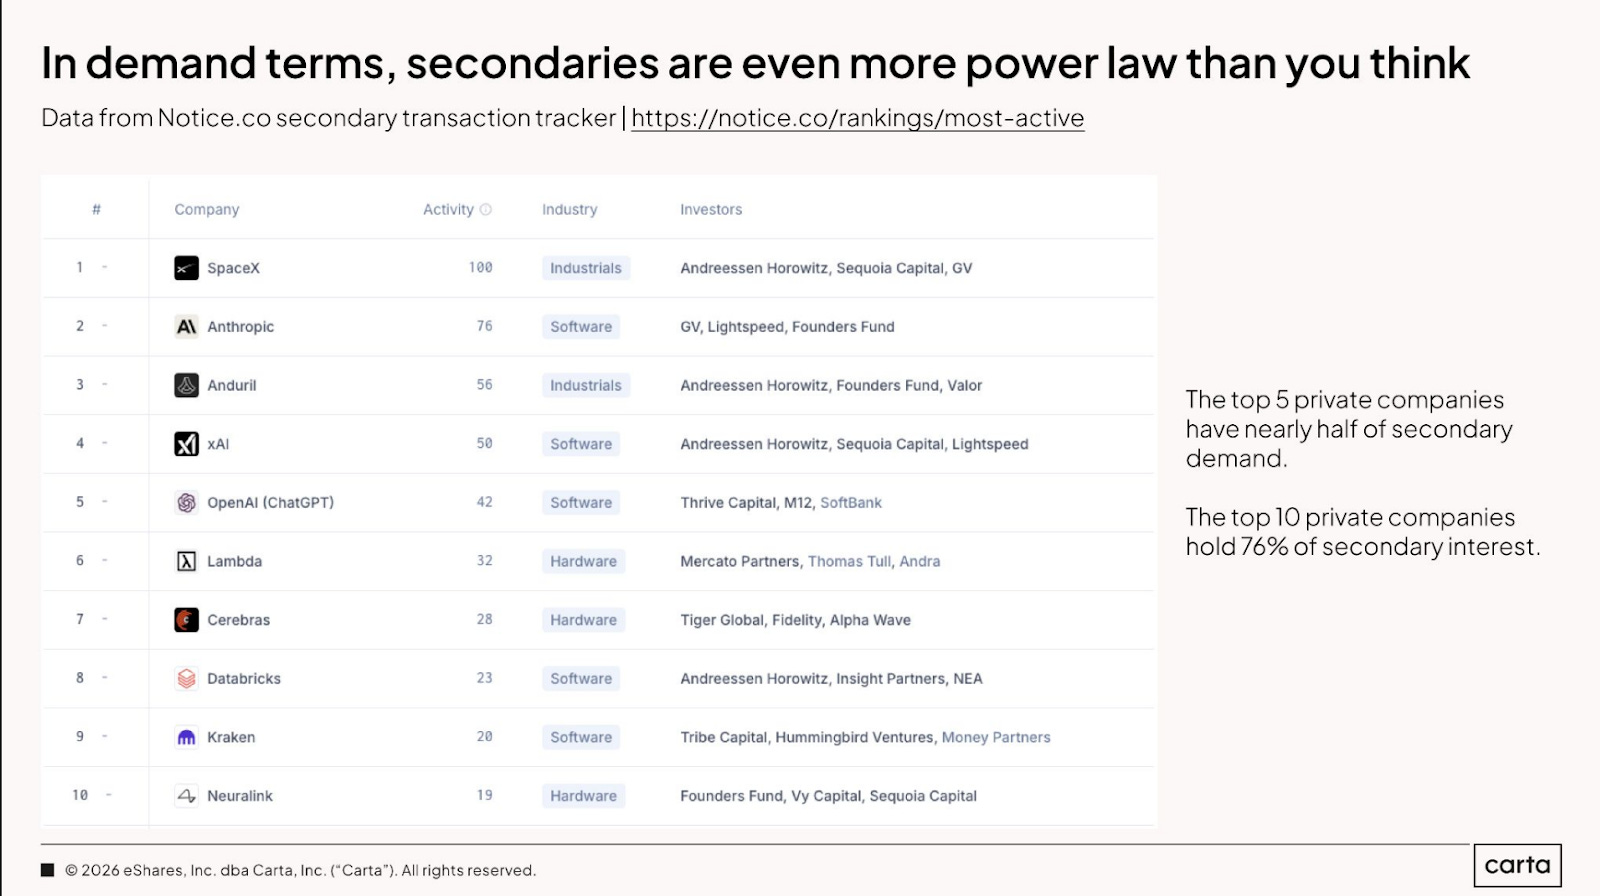
This is scary, and calling this a ‘secondary market’ is a real stretch. This is a small handful of bets that the entire industry is crowded into, and everyone is complicit.
When secondary demand is this concentrated, it tells you something important about where LP capital is flowing, where fund managers feel pressure to participate, and ultimately, where valuations get distorted beyond any rational underwriting. For the companies outside that top 10? The market is effectively closed.
Big Funds Have Outgrown Their Strategy And Their Founders
There are over 2,000 venture firms and more than 3,500 active funds. And at the peak, 82 venture funds over $1B closed in a single year. In the last 18 months, 10 firms have raised ~75% of all capital for the venture market.
Here’s the problem with that: a $1B+ fund cannot write a $10M check and move the needle. The math simply doesn’t work. So those funds have migrated upmarket. They are chasing the same late-stage, high-valuation names, pushing into buyouts, crossover strategies, and pre-IPO. What was once an early-stage or growth fund now looks like a multi-asset platform. Some of them are even holding pre-IPO company access hostage, so they can force RIAs (read: your retirement plans) into private fund vehicles (read: higher fees, low liquidity), rather than into public companies (read: lower fees, more liquidity).
But the true collateral damage is best (worst?) observed with the impact to founders. With so much concentration on high-visibility companies and massive funding rounds, founders building meaningful, capital-efficient businesses are effectively invisible to most institutional capital. Not because the opportunity isn’t there, but because the fund sizes have outgrown them and there is no courage to invest in companies beyond a shadow of a doubt. Nobody gets fired for hiring Goldman Sachs.
The Carta Data Validates Supercruise
Two charts from the Carta report are particularly relevant to how we think about investing at Supercruise.
First: seed-stage unicorn hit rates are highest when investing the top quartile of valuations: 5.6% versus 0.8% at the bottom. Sure, some are unicorns on their seed rounds these days. And paying for quality matters. We agree. You’ll find this commentary all over Twitter/X.
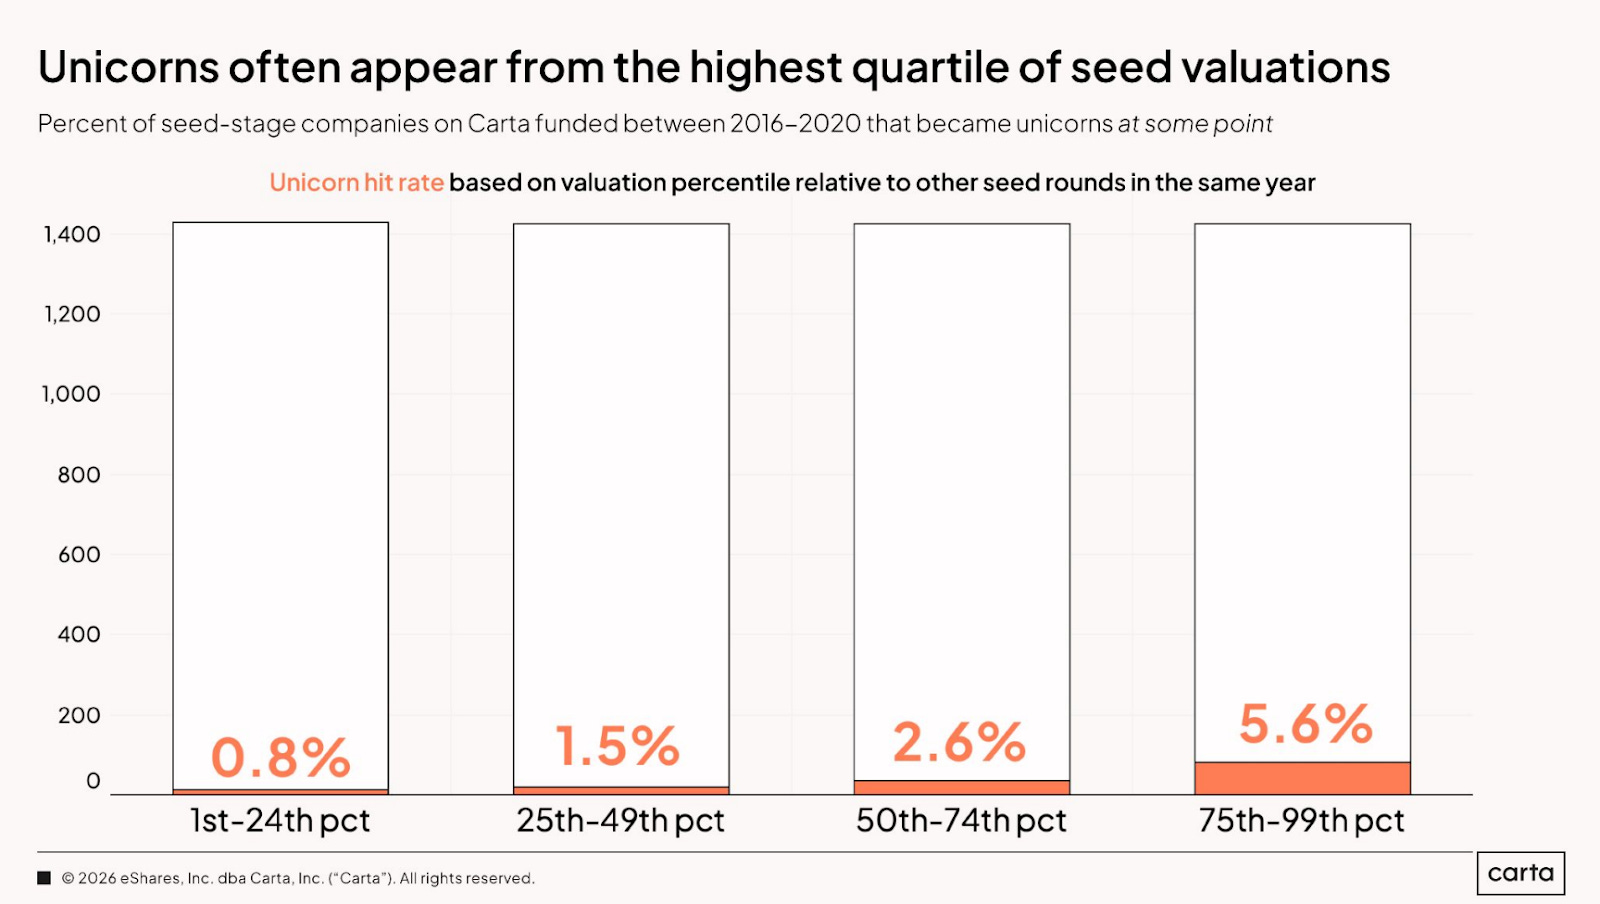
But does the top price necessarily mean it’s truly the best company? If so, how did Qualtrics, Atlassian, Surge.ai, and so many more even survive without raising for so long (or ever)? We’re disciplined about backing companies that have already demonstrated product-market fit and capital efficiency. That’s our north star for quality. And that’s how these companies thrived.
Second, and this is the more nuanced point: companies achieving 25x returns from their seed valuation are distributed across the valuation spectrum, with only modest variation between the bottom and top quartiles (10.6% versus 8.8%, respectively, and perhaps surprisingly).
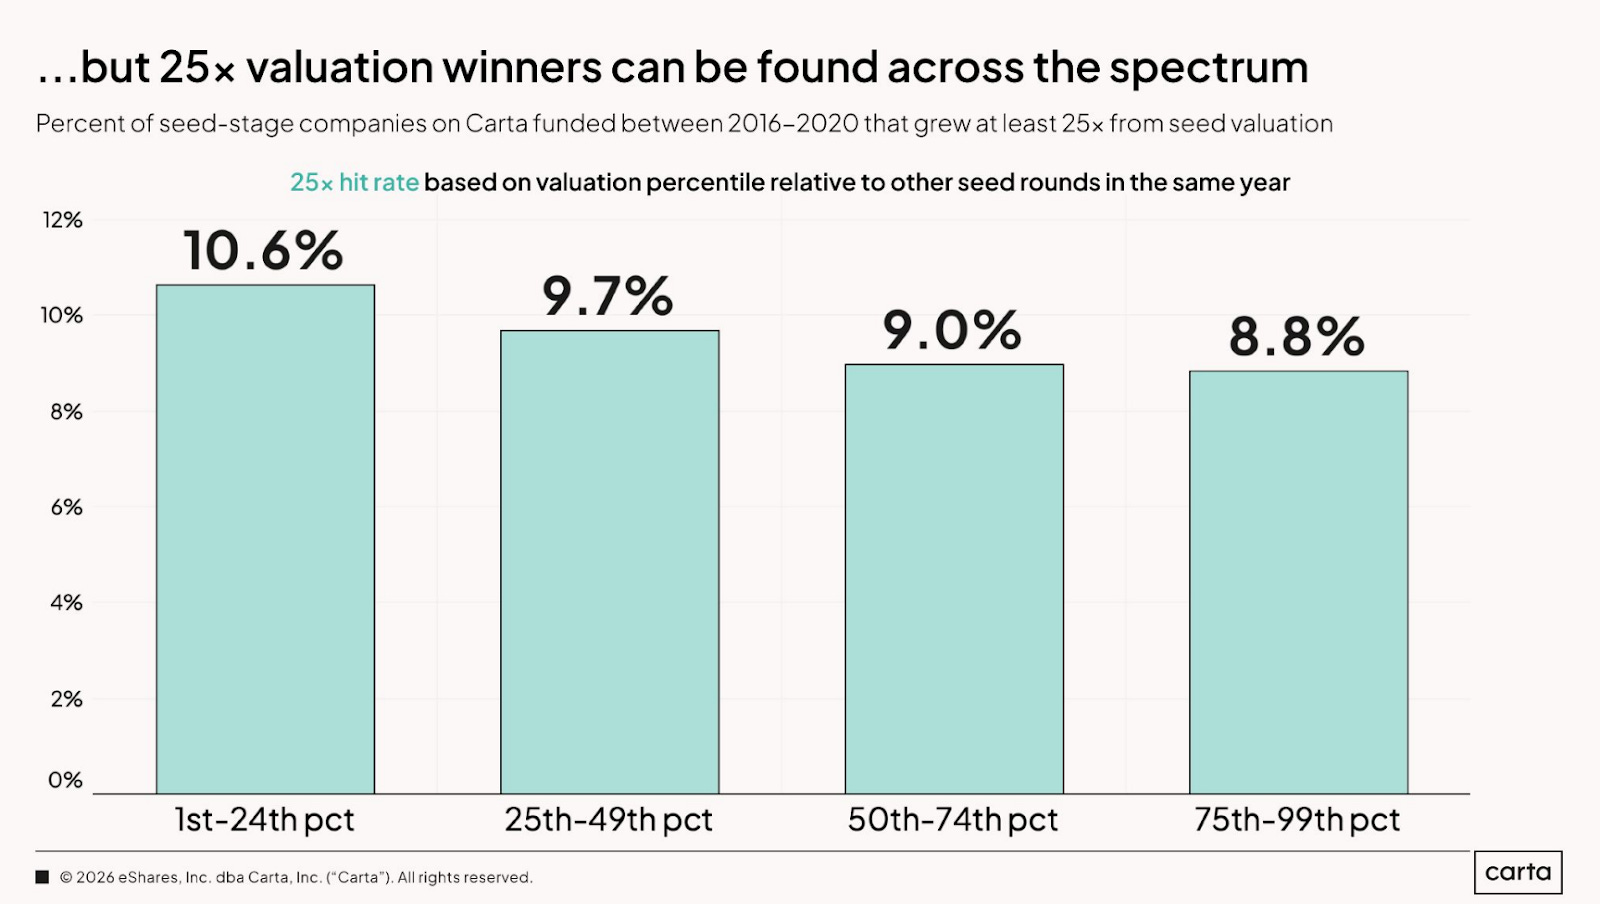
The highest-priced deals do not have a monopoly on great returns. Great returns are hiding in plain sight, in companies that the biggest funds have been designed to structurally ignore. For funds like Supercruise, the opportunity exists in the expanding market of companies that, for one reason or another, are overlooked by so many.
This is exactly the white space Supercruise is built to occupy.
Where We Fit And Why the Timing Has Never Been Better
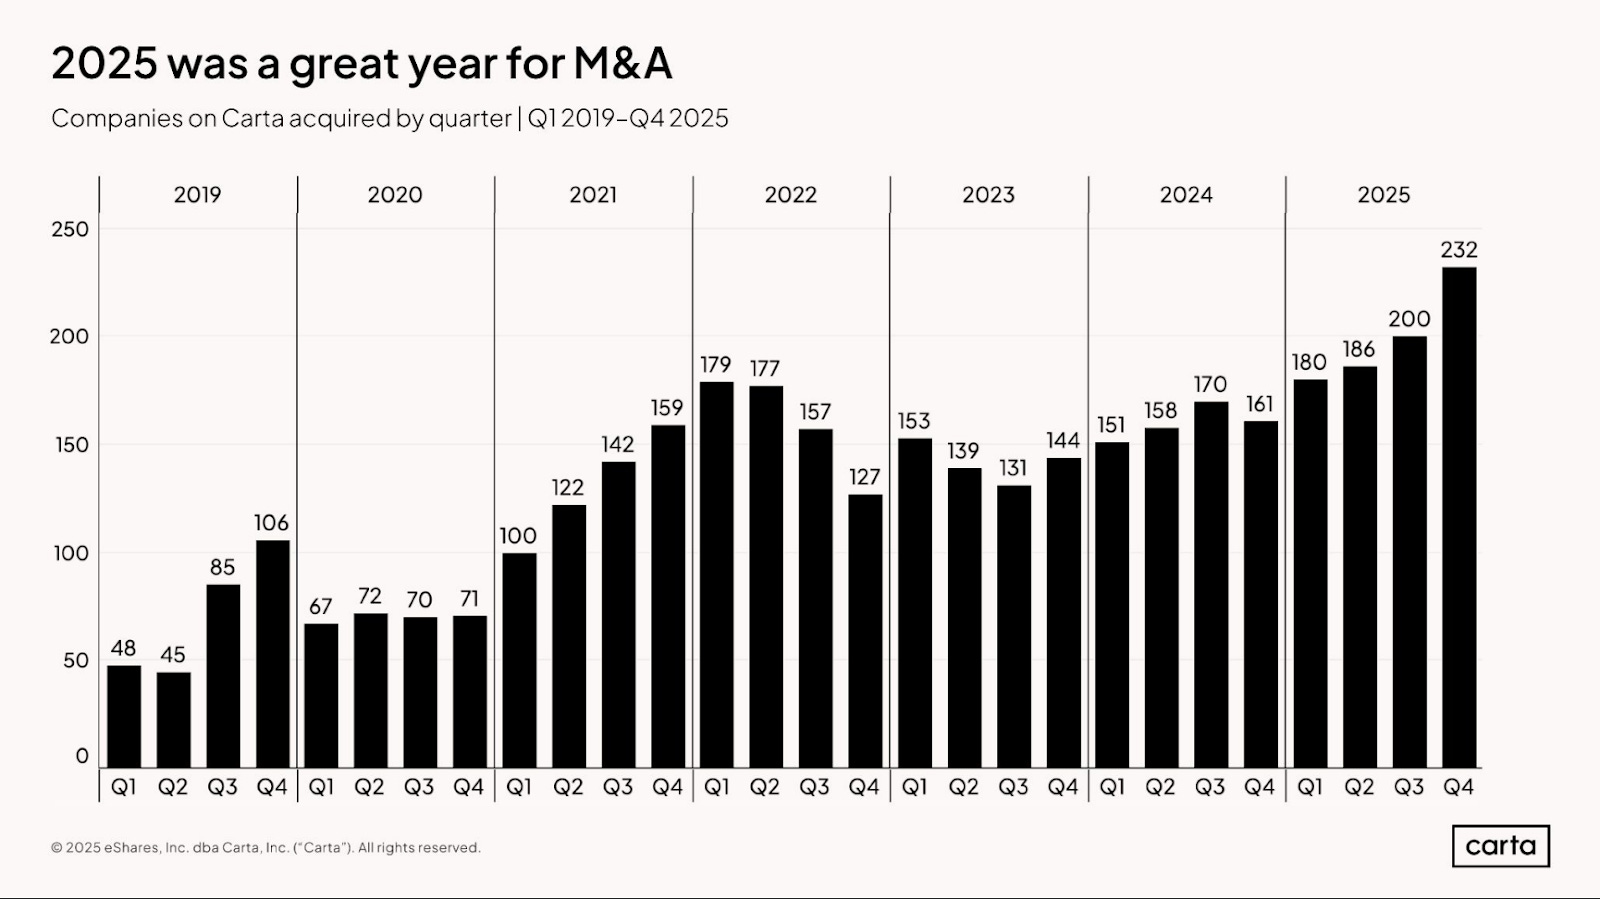
The Carta data also shows that M&A activity surged in 2025, with pre-seed acquihires growing fastest of all. The IPO market, while improving, remains well below 2021 levels.
And tender offers are back above their 2021 peak, with 47 executed in Q4 2025 alone.
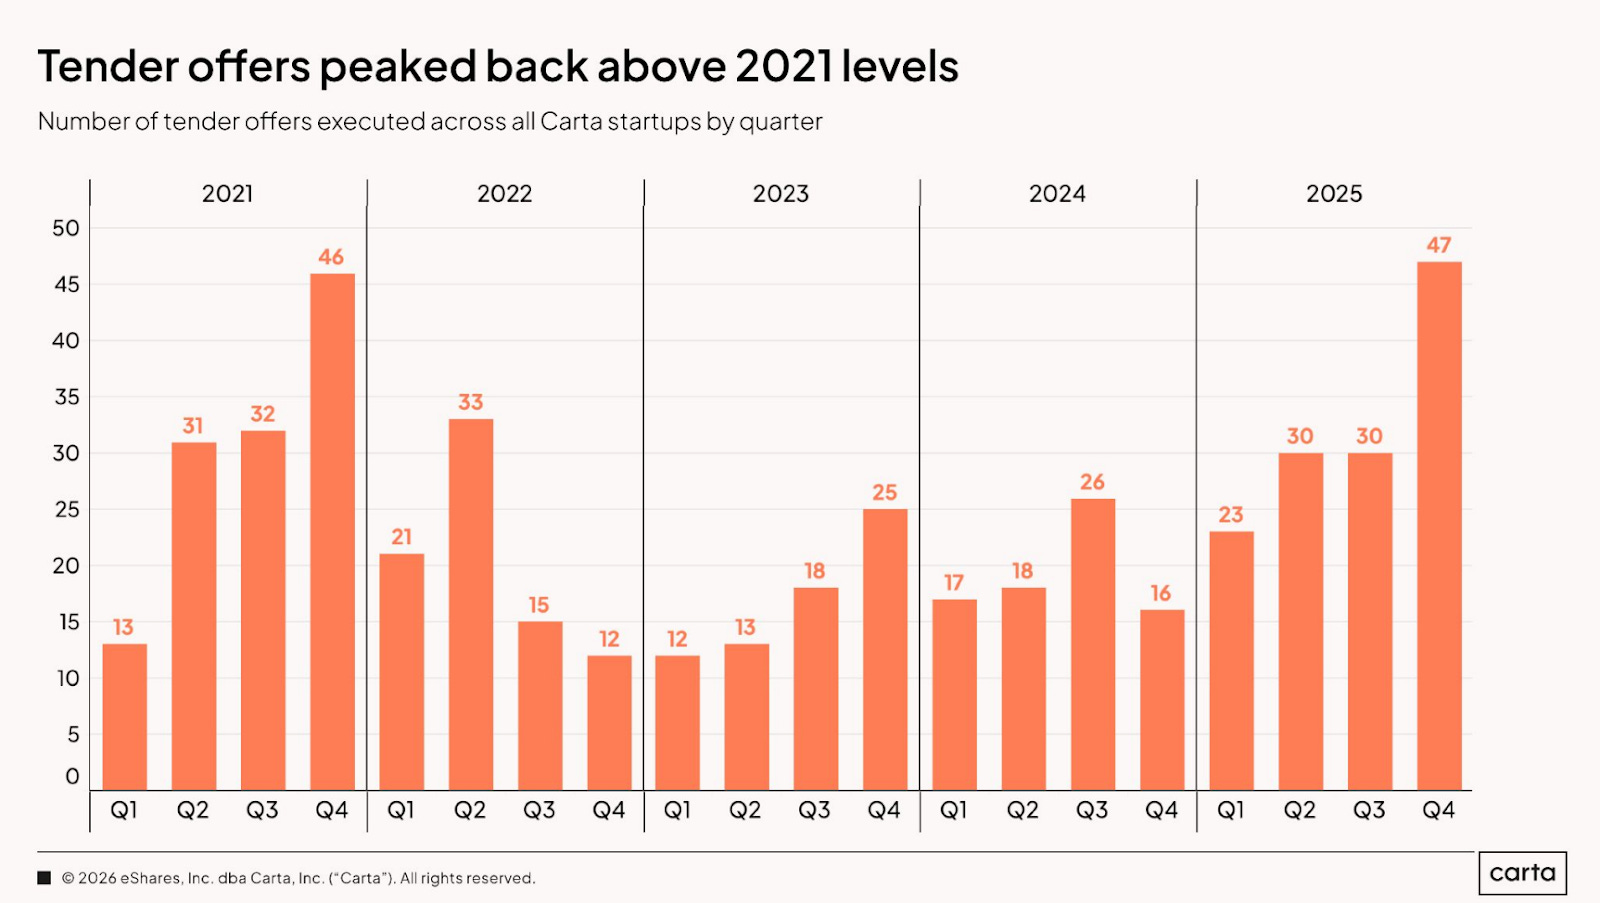
What does this tell us? Founders and employees want exits that don’t require a $10B IPO to return capital. They want liquidity pathways that match the actual scale of their businesses, and they’re increasingly skeptical of the traditional VC model - the one that requires you to raise indefinitely, hire aggressively, and eventually either go public or get acquired at a valuation that only makes sense if your last round was priced for the stars.
The Concentration Problem Is Our Opportunity
The same forces creating the bifurcated market Carta describes are the ones creating the opportunity we’re pursuing. When capital concentrates at the top, it leaves extraordinary companies underserved at the early growth stage. As fund sizes grow (and grow and grow), it creates a structural gap that a focused, right-sized fund can fill. It all comes back to alignment.
We’re hunting for the companies that only our systems (we call them Boresight and Overwatch) can detect. We can do this because we’ve spent years building the systems, the relationships, and the sector knowledge to find them before the crowd arrives. And for these structurally profitable businesses, for the crowd, it may be too late.
The venture market is breaking in two. We built Supercruise to thrive in the half that everyone else (wrongly) is ignoring.
Hi Morgan! I hope you're doing well. The venture market is breaking into two with boutique (specialist) funds and mega-funds. I think mega-funds are these days what is called "consensus capital" as they're betting on the same sector on the same companies in late-stage rounds. This is because they do not want a $1B outlier. They want a $10B outlier to move their fund's needle. The funds in the middle will either have to downsize or raise more. In my opinion a smaller fund would mean better return for LPs as you don't need mega-outcomes to move the needle.
I write a blog in substack titled "The LegalTech Thesis" wherein I analyze LegalTech startups and trends and identify opportunities to build in the space. Would love to get your thoughts on my post analyzing three such white spaces for 2026.
https://harshithviswanath.substack.com/p/three-legaltech-whitespace-plays